 (773) 843-3333
 hello@4myins.com

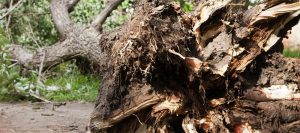 If a tree falls after a storm and hits your office building, is the damage covered by your business insurance? The answer? Well, it depends (on your policy).
Here are three things to know about business insurance and toppled trees.
1. Coverage details
You’re covered for the removal of the fallen trees and related damages if your policy specifically covers and lists your building and other property, such as fences, freestanding signs and outbuildings. This includes trees felled by a windstorm, lightning, hail or from the weight of ice, snow or sleet; but it doesn’t cover diseased or dead trees.
What if the tree lands on your work vehicle? If comprehensive coverage is purchased for your business vehicles, damage from fallen trees would be covered.
2. Where the tree falls is key
Where a tree falls is generally more important to an insurance company than its owner. So if the neighbor’s tree lands on your business property, you would file a claim with your insurance company.… Read More
Three Things to Know about Fallen Trees and Business Insurance
If a tree falls after a storm and hits your office building, is the damage covered by your business insurance? The answer? Well, it depends (on your policy).
Here are three things to know about business insurance and toppled trees.
1. Coverage details
You’re covered for the removal of the fallen trees and related damages if your policy specifically covers and lists your building and other property, such as fences, freestanding signs and outbuildings. This includes trees felled by a windstorm, lightning, hail or from the weight of ice, snow or sleet; but it doesn’t cover diseased or dead trees.
What if the tree lands on your work vehicle? If comprehensive coverage is purchased for your business vehicles, damage from fallen trees would be covered.
2. Where the tree falls is key
Where a tree falls is generally more important to an insurance company than its owner. So if the neighbor’s tree lands on your business property, you would file a claim with your insurance company.… Read More
 There’s no denying that home-based businesses are on the rise. Right now, it’s estimated that there are 38 million home-based businesses that generate $427 billion a year in the United States.
 Many trends in today’s business world are exciting and encouraging. Unfortunately, the number of lawsuits and high-dollar awards in liability cases are not one of those positive trends. Here are a few recent news headlines from around the country:
Pennsylvania hotel sued for concussion from shower slip.
Fatal two-truck accident case in New York results in $3.97 million settlement.
Virginia victims get settlement checks (about $9 million) over toxic drywall.
There’s no way to prevent lawsuits like these entirely, but you can manage the impact. A business catastrophe liability policy serves as financial protection, or a cushion, against a legal judgment for a covered loss, beyond the limits of your underlying insurance policies.
A business catastrophe liability policy functions in a similar fashion to a personal catastrophe liability policy. Personal catastrophe liability —commonly known as “umbrella” – coverage can provide an extra layer of liability protection over and above your auto and homeowners policies in the event that a covered claim is made against you (or a covered family member).…
 Many people today are enjoying the benefits of being their own boss and running their own company. According to the U.S. Census, there are currently more than 5 million companies with fewer than 20 people actively operating in this country. Whether you freelance or you have created a company that employs others, you can take advantage of a variety of tax deductions on your business income.
Owners of large corporations have accountants and tax experts working for them, but many small-business owners and freelancers cannot afford that added expense. If you complete your tax returns on your own each year, make sure that you are aware of the tax deductions you can use to save. Some of the most common business deductions are listed below.
Home office
According to Entrepreneur Magazine, approximately 52 percent of all businesses in America are operated out of the business owners’ homes. The home office deduction, therefore, is one that may be useful to many.…


 A few of the other coverages that restaurant owners often need include coverage for property damage related to an off-premises utility failure; employee dishonesty and theft; sewer and drain backup; and dish and glass breakage.
As you can see, restaurant insurance is important—and complex. To get some peace of mind about your coverage, it’s important to speak with an insurance professional.…